
Knowledge Center
UK Debt Help Knowledge Centre
Expert guides and practical articles covering CCJs, personal guarantees, debt collection, creditor letters, bailiffs, bankruptcy and business debt. Understand your position, your rights and what options may be available
Clarity.
Time.
Choice.
Control.
Free UK Debt Help Guides
In-depth guides written to help individuals and company directors understand debt, creditor action and the options available to them
UK Debt Help Knowledge Centre
Clear, practical guides and articles to CCJs, creditor letters, personal guarantees, bankruptcy, business debt and enforcement and more...
What do you need help understanding? Read the latest.
How to Remove a CCJ: A Practical Guide
Debt Help, CCJ Removal
Can a CCJ Be Removed? Your Practical Guide to Getting Back on Track
A County Court Judgment (CCJ) can feel like a heavy label that follows you everywhere. If you’re wondering whether a CCJ can be removed, how it affects you, and what you can realistically do next, this guide from Stop Your Debt UK is designed to give you clear, compassionate answers.
What Is a CCJ and Why Does It Matter So Much?
A County Court Judgment is a court order stating that you owe money to a creditor and have not kept to the agreed repayment terms. Once recorded, a CCJ appears on your credit file for six years and is listed on the public Register of Judgments. This CCJ impact can be significant:
It can make it harder to obtain credit, mortgages, or even some mobile phone contracts.
Lenders may see a CCJ as a sign that you are a higher-risk borrower.
Your credit score CCJ relationship is direct: a CCJ almost always lowers your score.
The good news is that in some situations, CCJ removal is possible, and even when it isn’t, there are ways to reduce its impact and start rebuilding your financial health.
Can a CCJ Be Removed from Your Credit File?
Whether you can remove a CCJ depends on your circumstances. There are three main routes individuals should know about:
1. Paying the CCJ in Full Within One Month
If you pay the total amount owed (including any court fees) within one calendar month of the judgment date, you can apply to have the CCJ completely removed from the Register of Judgments and, in turn, your credit file. This is the most straightforward form of CCJ removal, but it is only available in that early one‑month window.
2. Setting Aside a CCJ That Shouldn’t Have Been Issued
If you believe the CCJ was issued unfairly or incorrectly, you may be able to ask the court to “set aside” the judgment. This is not automatic and usually requires strong reasons, such as:
You never received the claim form or paperwork.
You had already paid the debt before the judgment was made.
You dispute owing the debt or the amount claimed.
If the court agrees and sets aside the judgment, it is as if the CCJ never existed, and it should be removed from your credit file. This process can be complex, so it’s wise to seek guidance before applying. At Stop Your Debt UK, we regularly help individuals assess whether applying to set aside is appropriate for their situation.
3. Waiting for the Six-Year Expiry
If you cannot pay within one month and the judgment is not set aside, the CCJ will usually stay on your credit file for six years from the judgment date, even if you later pay it in full. After six years, it is automatically removed from your credit report. This is not an active way to remove CCJ, but it does mean the CCJ will not follow you forever.
💡 Pro Tip: Even if a CCJ cannot be removed immediately, paying it and keeping to any agreed instalments can still improve how future lenders view you.
How a CCJ Affects Your Everyday Life and Credit Score
The CCJ impact goes beyond numbers on a credit report. You might notice:
Applications for credit cards, loans, or car finance being declined or offered at higher interest rates.
Difficulty remortgaging or moving to a new rental property if credit checks are required.
Increased stress and anxiety around money and future plans.
Understanding how a credit score CCJ link works is the first step. The second is having a clear, structured plan to deal with the judgment and your wider debts so you can start moving forward again.
Reviewing your credit file is a critical first step in tackling CCJs effectively.
Your Next Steps: From Confusion to Clarity
If you’re facing a CCJ, you do not have to figure everything out alone. At Stop Your Debt UK, we focus on giving you clarity, time, and control so you can make informed decisions at your own pace. For a deeper understanding, our Guide to CCJs explains the entire process from start to finish, including what happens before a judgment, how enforcement works, and your rights at every stage.
You can access The Complete Guide To CCJ’s in our free downloadable section – it’s a comprehensive CCJ free download designed to answer the questions most individuals have but are often too stressed to ask. Inside, you’ll find practical examples, timelines, and checklists to help you understand your options, including when and how CCJ removal might be possible in your situation.
When to Get Personalised Support
Every person’s circumstances are different. You might be juggling multiple debts, worried about your home or business, or feeling overwhelmed by letters and calls. That’s why generic advice can only go so far. A personalised review of your situation can uncover options you may not realise you have, from affordable repayment plans to formal solutions that protect you from further pressure.
At Stop Your Debt UK, we combine professional expertise with genuine understanding. Our role is not to judge you, but to stand beside you while you regain control over your finances. If you’re unsure whether your CCJ can be removed, or how to manage its impact, we can walk you through the choices step by step.
Take the First Step Towards a Fresh Start
A CCJ can feel like a permanent stain on your record, but it does not define you and it does not have to dictate your future. Understanding when you can remove a CCJ, how long it will last, and what you can do in the meantime is empowering. Coupled with a clear plan for your wider debts, it can be the beginning of a genuine fresh start.
Download The Complete Guide To CCJ’s from our free resources today to deepen your knowledge, then book a free consultation with Stop Your Debt UK for a personalised assessment. Together, we can explore your options, reduce the CCJ impact on your life, and help you move towards a more secure financial future with clarity, choice, and control.

What Does This Letter Actually Mean?
Try LetterChekr™
Three Simple Steps
1. Upload Your Letter
Take a clear photograph of the letter or upload your document.
You don't need to understand what it says before uploading it.
2. Understand What It Means
LetterChekr™ reviews the contents and explains the important information in plain, straightforward English.
3. Understand What May Happen Next
You'll receive clear information about the urgency of the correspondence, important dates, potential consequences and the general processes that may follow.
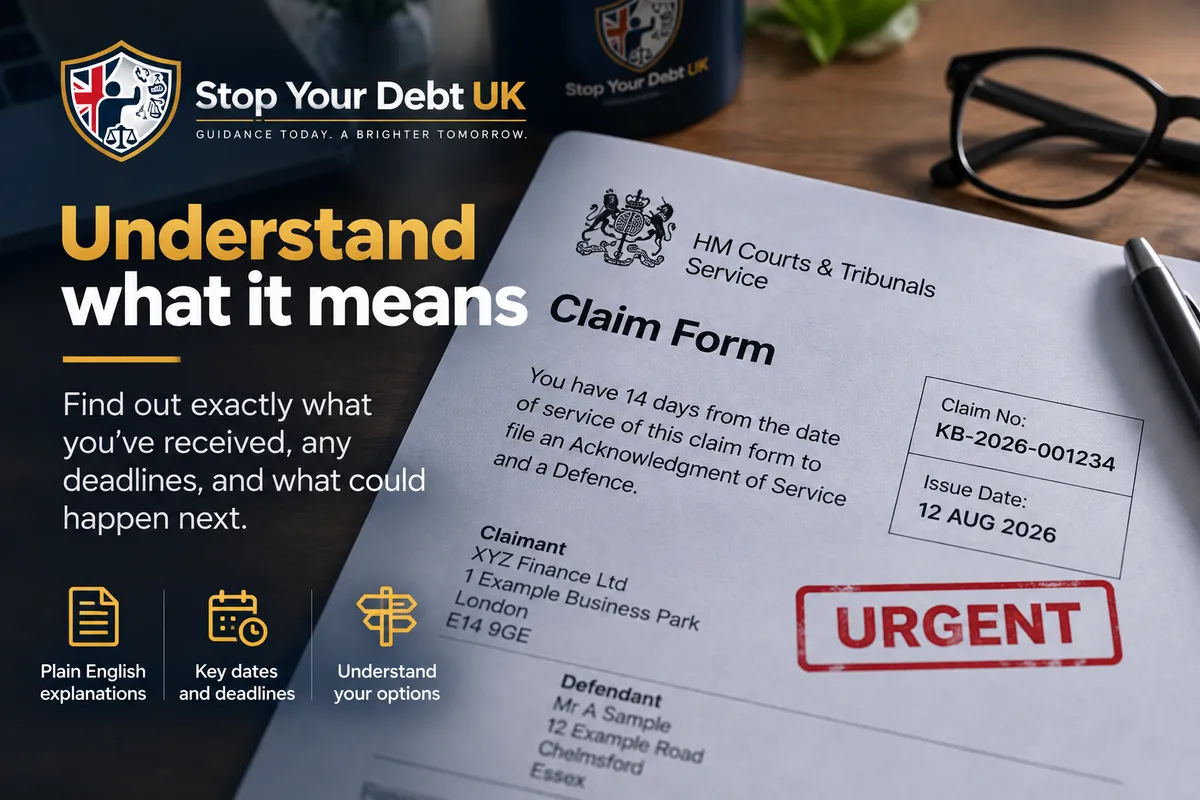
LetterChekr™
Book a Call With a Consultant
Complete your details below and one of our consultants can discuss the letter with you and help you understand the options available.
That's it. In around 30 seconds, you'll receive a plain-English explanation of your letter.
Stop Your Debt UK is a national debt support platform helping individuals and company directors understand financial problems, organise their position and access the appropriate professional support when specialist or regulated advice is required.
Quick links
Services
Stop Your Debt UK is not an FCA-authorised debt advice firm or an SRA-regulated law firm. Where regulated or reserved professional services are required, the relevant work is undertaken by an appropriately authorised third-party professional. Learn More
© Stop Your Debt UK. 2026. All Rights Reserved.