
Knowledge Center
UK Debt Help Knowledge Centre
Expert guides and practical articles covering CCJs, personal guarantees, debt collection, creditor letters, bailiffs, bankruptcy and business debt. Understand your position, your rights and what options may be available
Clarity.
Time.
Choice.
Control.
Free UK Debt Help Guides
In-depth guides written to help individuals and company directors understand debt, creditor action and the options available to them
UK Debt Help Knowledge Centre
Clear, practical guides and articles to CCJs, creditor letters, personal guarantees, bankruptcy, business debt and enforcement and more...
What do you need help understanding? Read the latest.
Mortgage Options with a CCJ: Your Guide
Debt Help, CCJ, Mortgage Options
Can I Get a Mortgage with a CCJ?
If you have a County Court Judgment (CCJ) on your credit file, it can feel like home ownership is out of reach. The reality is more hopeful: you may still be able to get a mortgage with a CCJ, especially if you understand your options and prepare carefully. At Stop Your Debt UK, we help people in exactly this position every day, which is why we’ve created a free, practical CCJ Guide to support you through the process.
What Is a CCJ and How Does It Affect a Mortgage?
A CCJ is a court order issued when you fail to repay money you owe. It appears on your credit file for six years and can significantly impact your ability to borrow, including applying for a mortgage. Lenders see a CCJ as a sign that you have previously struggled to manage debt, so they may view you as higher risk.
However, a CCJ does not automatically mean a “no”. Many lenders, particularly specialist and Bad Credit Mortgage providers, will consider applications from people with historic or even recent CCJs, as long as the rest of the application shows that your situation is stable and improving.
Can I Get a Mortgage with a CCJ?
In many cases, yes, you can get a mortgage with a CCJ. The outcome will depend on a few key factors:
How old the CCJ is: The older the CCJ, the less weight some lenders place on it, especially if you have managed your finances well since then.
Whether the CCJ has been satisfied: If you have repaid the debt in full and it is marked as “satisfied”, this can improve your chances of being accepted for a mortgage.
The size of the CCJ and any other debts: Larger judgments or multiple debts may limit the number of lenders willing to help, but specialist Mortgage Options are still often available.
Your recent credit behaviour: Demonstrating a pattern of on-time payments and responsible borrowing since the CCJ is crucial.
💡 Pro Tip: Before speaking to any lender, download our free CCJ Guide from Stop Your Debt UK. It explains, step-by-step, how to check your credit file, deal with old judgments and present your situation clearly to potential lenders.
Bad Credit Mortgage Lenders and Specialist Mortgage Options
Mainstream high-street banks often have strict criteria and may decline applications involving a recent CCJ. But they are not your only route. There are specialist lenders who focus on Bad Credit Mortgage products designed for people with:
CCJs and defaults
Missed or late payments
Debt management plans or previous arrangements with creditors
These lenders assess applications more flexibly, looking at the overall picture rather than just a credit score. They will consider your current income, affordability, deposit size, and how you’ve handled your finances since the CCJ was registered. This can open the door to realistic Mortgage Options even when your credit file is less than perfect.
Specialist lenders can offer tailored mortgage options even after a CCJ.
How to Improve Your Chances of Getting a Mortgage with a CCJ
While a CCJ will always be a consideration, there are practical steps you can take to strengthen your application and move closer to a successful mortgage offer:
Check your credit file: Make sure the CCJ details are accurate and that any satisfied CCJs are correctly recorded. Our free CCJ Guide walks you through how to do this and what to look for.
Clear or settle outstanding debts where possible: Reducing your overall debt level and settling older CCJs can make you more attractive to lenders.
Build a track record of on-time payments: Consistent, reliable payments on existing commitments show that your financial behaviour has changed for the better.
Save a larger deposit if you can: A higher deposit reduces the lender’s risk and may unlock better Mortgage Options and interest rates, even on a Bad Credit Mortgage.
Seek specialist advice: A professional adviser who understands CCJs and bad credit lending can guide you towards the most suitable lenders and products.
How Stop Your Debt UK and Our Free CCJ Guide Can Help
At Stop Your Debt UK, we understand that a CCJ is often the result of a difficult period in your life, not a reflection of who you are today. Our role is to give you clarity, time, and control so you can make informed decisions about your debts and your future, including your plans to secure a mortgage.
That’s why we created our free downloadable CCJ Guide. Inside, you’ll find:
Clear explanations of how CCJs work and how they affect your credit profile
Practical steps for checking, challenging, or satisfying a CCJ
Guidance on preparing for a mortgage application when you have bad credit
You can download the CCJ Guide for free directly from the Stop Your Debt UK website and use it alongside personalised advice to move forward with confidence.
Take the Next Step Towards a Mortgage After a CCJ
Having a CCJ on your record can feel overwhelming, but it does not have to be the end of your home ownership plans. With the right information, careful preparation, and support from experienced professionals, a mortgage with a CCJ is often still achievable through specialist Bad Credit Mortgage lenders and tailored Mortgage Options.
If you are unsure where to start, we are here to help. Book a free consultation with Stop Your Debt UK to receive a personalised assessment of your situation, explore realistic mortgage routes, and begin rebuilding your financial future. Download our free CCJ Guide today, and take the first step towards turning a difficult chapter into a new beginning.

What Does This Letter Actually Mean?
Try LetterChekr™
Three Simple Steps
1. Upload Your Letter
Take a clear photograph of the letter or upload your document.
You don't need to understand what it says before uploading it.
2. Understand What It Means
LetterChekr™ reviews the contents and explains the important information in plain, straightforward English.
3. Understand What May Happen Next
You'll receive clear information about the urgency of the correspondence, important dates, potential consequences and the general processes that may follow.
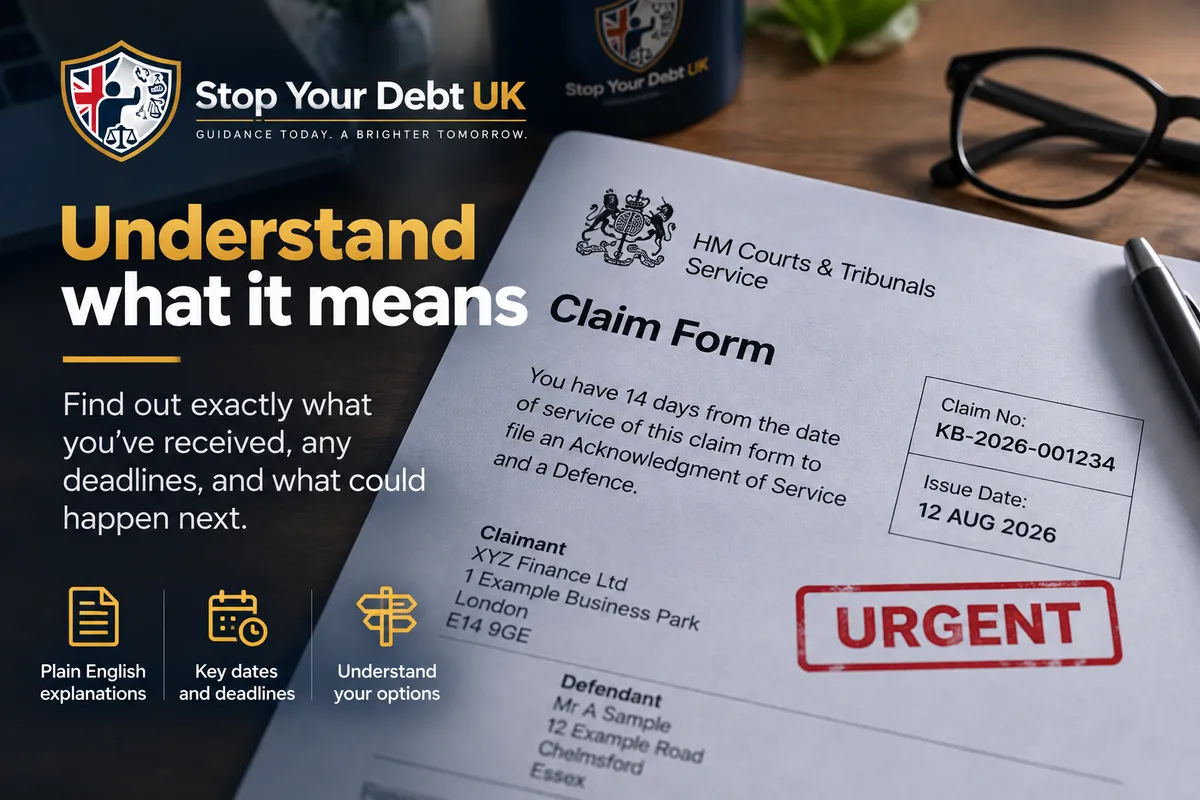
LetterChekr™
Book a Call With a Consultant
Complete your details below and one of our consultants can discuss the letter with you and help you understand the options available.
That's it. In around 30 seconds, you'll receive a plain-English explanation of your letter.
Stop Your Debt UK is a national debt support platform helping individuals and company directors understand financial problems, organise their position and access the appropriate professional support when specialist or regulated advice is required.
Quick links
Services
Stop Your Debt UK is not an FCA-authorised debt advice firm or an SRA-regulated law firm. Where regulated or reserved professional services are required, the relevant work is undertaken by an appropriately authorised third-party professional. Learn More
© Stop Your Debt UK. 2026. All Rights Reserved.