
Understand the Situation. Know What Comes Next.
Explore clear, detailed information about personal debt, court and creditor problems, personal guarantees, company financial difficulty and UK debt options. Built to help you understand the landscape before deciding what support may be required.
Better information creates clearer options. Start with the subject that matters to you.
Start With Your Situation.
You don't need to know the technical name for the problem before you start.
Choose the area that most closely reflects what is happening. From there, explore detailed guides, answers to common questions and information about the different stages a financial problem can reach.
Personal Debt
Understand common personal debt problems, the different options that may exist and what can happen when payments become difficult to maintain.
Court & Creditor Problems
Learn what creditor contact, court claims, County Court Judgments and enforcement can mean, and understand how matters may progress.
Business Debt & Directors
Explore information about company financial difficulty, creditor pressure, formal insolvency processes and the issues directors may need to understand.
Personal Guarantees
Understand how personal guarantees can affect directors, what may happen when a guarantee is called upon and why the wording and circumstances matter.
Explore the wider UK debt help landscape.
Our Debt Help & Options hub explains the different areas of debt support and the professional pathways that may become relevant depending on the situation.
Go Deeper With Our Free UK Guides.
Some subjects need more than a short answer.
Our in-depth guides bring together the key concepts, processes and questions surrounding some of the most important debt, court and director issues in one structured resource.
The Complete Guide to CCJs
Understand what a County Court Judgment is, how CCJs happen, paying within 30 days, setting aside a judgment, enforcement, bailiffs, charging orders and the wider implications of a CCJ.
The Complete Guide to Personal Guarantees
Explore how personal guarantees work, when they may be called upon, lender demands, director exposure, company insolvency and why the wording and circumstances surrounding a guarantee matter.
The Complete Guide to Business Debt & Insolvency
A director-focused guide to company financial difficulty, creditor pressure, CVAs, CVLs, administration, liquidation, director exposure and the different routes that may become relevant.
More specialist guides will be added to the Knowledge Centre.
Alongside our long-form guides, you can explore individual articles answering specific questions about debt, creditors, court action, directors and insolvency.
Find the Information That Matters to You.
Debt problems rarely exist in isolation.
A missed payment can become creditor contact. Creditor action can become a court claim. Company financial difficulty can create questions about insolvency, directors and personal guarantees. Explore the subjects below to understand how the different pieces fit together.
Personal Debt
Understand the wider debt landscape, the main formal and informal routes and what each process is designed to address.
Court & Creditor
Follow the journey from creditor pressure and correspondence through court proceedings, judgments and potential enforcement.
Business Debt & Insolvency
Explore company financial difficulty, formal insolvency processes and the issues directors may need to understand as pressure develops.
Personal Guarantees
Understand the relationship between company borrowing, personal exposure, lender demands and what can happen when a business cannot meet its obligations.
Continue into our latest articles and question-led resources.
The Knowledge Centre is continually expanding with focused articles addressing the questions people ask when dealing with debt, creditors, court action and company financial difficulty.
Answers to the Questions People Actually Ask.
Understand one question at a time.
Explore practical, plain-English articles covering debt, creditor action, court processes, personal guarantees and company financial difficulty. New resources are added as the Knowledge Centre continues to grow.
Latest from the Knowledge Centre
LATEST ARTICLES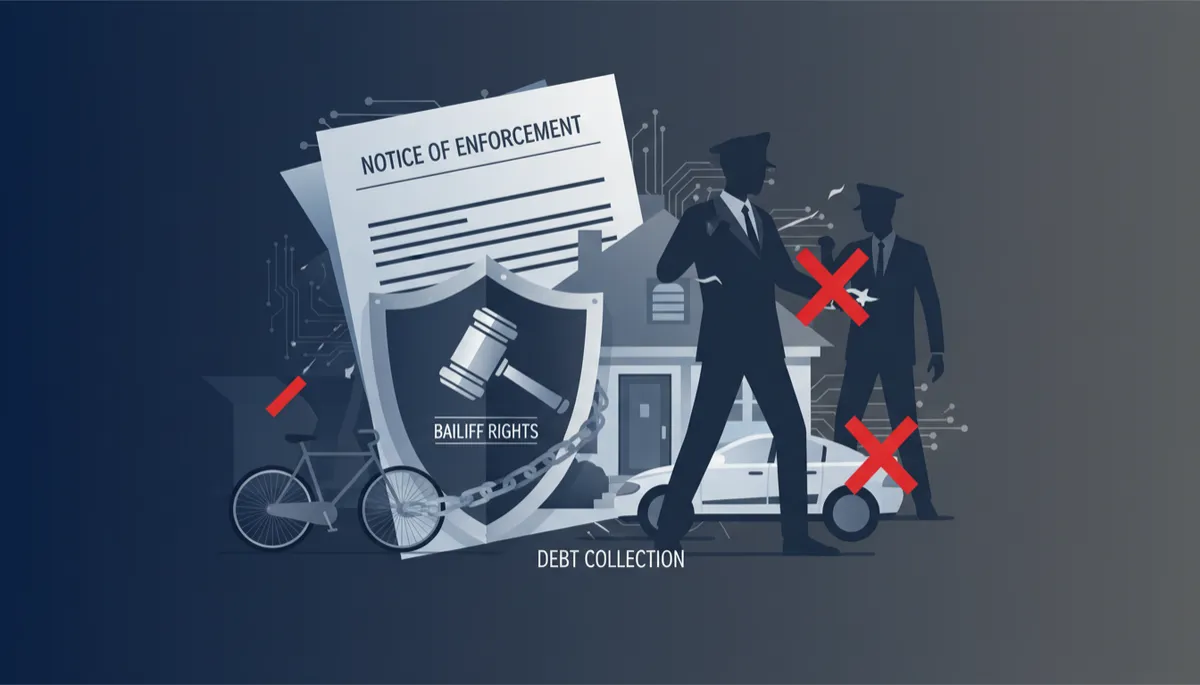
Know Your Rights: Bailiffs & Enforcement Notices
Bailiffs, Notice Of Enforcement, Debt Collection, Bailiff Rights
Notice of Enforcement and Bailiffs: Know Your Rights Before You Open the Door
If you have received a Notice Of Enforcement or been told that bailiffs are on their way, it can feel frightening and overwhelming. Understanding what bailiffs can and cannot do is the first step to taking back control and protecting yourself, your family, and your essential belongings. This guide from Stop Your Debt UK explains your bailiff rights in clear, practical language so you can respond calmly and confidently.
What Is a Notice Of Enforcement?
A Notice Of Enforcement is a formal letter sent by enforcement agents (commonly called bailiffs) to tell you they intend to collect a debt. It usually follows a court judgment or liability order and is part of the debt collection process. By law, the notice must give you at least seven clear days’ warning (not counting the day it is sent or the day of the visit) before a bailiff can come to your property, except in very rare circumstances.
The Notice Of Enforcement should clearly state:
Who the creditor is and how much you allegedly owe
Which enforcement company or bailiff is acting on their behalf
How to contact them and arrange payment or discuss the debt
The date from which a bailiff may visit if no agreement is reached
💡 Pro Tip: Receiving a Notice Of Enforcement is often the last warning before bailiff action. It is also a key opportunity to get help. Contacting a specialist, such as Stop Your Debt UK, at this stage can open up options and may prevent a visit entirely.
What Bailiffs Can Legally Do
While bailiffs have specific powers, they are not all-powerful. Knowing the limits of their authority helps you recognise when their behaviour crosses the line. In general, a certificated bailiff acting on a court order can:
Visit your home or business to collect payment for certain types of debts, such as council tax, parking fines, court fines, and some business debts
Ask you to pay the debt in full or agree to a repayment plan, often called a controlled goods agreement, where some non-essential items are listed as security
Take control of certain non-essential goods you own, either at your property or on the public highway, to be sold if you do not keep to an agreement
Even when they are acting within the law, bailiffs must follow strict rules on behaviour and conduct. They must treat you fairly, provide identification when asked, and clearly explain the reason for their visit and the amount they are claiming. Debt collection should never feel like harassment or intimidation.
What Bailiffs Cannot Do – Your Core Protections
Just as important as what bailiffs can do is what they cannot do. Many people are pressured into paying money they simply do not have because they are given a misleading picture of bailiff powers. Understanding your bailiff rights is essential to staying safe and making rational decisions.
They cannot break and enter your home
For most types of debt, bailiffs cannot break into your home. They are only allowed to enter through what is known as “peaceful entry”. That means:
You open the door and invite them in, or you step aside and clearly allow them to enter, or
They enter through an unlocked door or gate without using force
They cannot:
Push past you or force their way through the door if you are blocking it
Climb through a window, break a lock, or damage doors, windows, or gates to get inside
There are very limited exceptions for certain criminal fines and HMRC debts, but even then, strict procedures apply and most household debts do not fall into this category. For the vast majority of people facing council tax, parking fines, or consumer debts, you are under no obligation to let a bailiff into your home, and they are not allowed to break in.
📌 Key Takeaway: If you keep your doors locked and do not invite them in, a bailiff collecting most common debts cannot lawfully enter your home by force.
They cannot take essential possessions such as a work car or bike
Bailiffs are also restricted in what they can take. The law recognises that some items are essential for living and earning a living. These are protected because taking them would push you further into hardship and make it even harder to repay debts in the long term.
In most cases, bailiffs cannot take possessions that are deemed necessary, such as:
Tools, equipment, and books that you need to do your job or run your business, up to a certain value
A work car or bike that you reasonably need to travel to work, carry out your job, or get to medical appointments, again within set value limits
Basic household items such as your cooker, fridge, beds, clothing, and essential furniture
If a bailiff threatens to remove an item you rely on for work or essential living, you have the right to challenge this and should seek immediate advice. At Stop Your Debt UK, we frequently help clients contest attempts to take protected goods and ensure that enforcement agents stick to the rules.
Vehicles genuinely needed for work are often protected from bailiff seizure.
How Some Bailiffs Break the Rules and Use Scare Tactics
Despite clear regulations, many people report that bailiffs break the rules or stretch them to the limit. Complaints often centre on aggressive behaviour, misleading statements, and deliberate attempts to frighten people into paying money they simply cannot afford. Sadly, scare tactics are common in debt collection, especially when individuals do not know their rights.
Common scare tactics include:
Claiming they can “come back with a locksmith” or “break in later today” when they have no legal power to do so for your type of debt
Threatening to “take everything” or leave you with no furniture, which is not allowed under bailiff regulations
Suggesting you could be arrested or imprisoned simply for not paying, which is rarely true and does not apply to most civil debts
These tactics are designed to trigger panic. When you are scared, you are more likely to hand over rent money, food money, or business cash just to make the situation go away. This can leave you unable to meet other essential bills and deepen your overall debt problems. Knowing that a bailiff cannot enter your home by force and cannot take essential possessions gives you the breathing space to seek proper advice before agreeing to anything.
💡 Pro Tip: If you feel pressured or threatened, you are allowed to end the conversation, keep the door closed, and speak to a professional adviser. You do not have to make decisions on the doorstep.
Practical Steps If You Receive a Notice Of Enforcement
When a Notice Of Enforcement lands on your doormat, it is natural to feel anxious. But you are not powerless. Taking a few calm, practical steps can transform the situation and often prevent the worst outcomes of bailiff action.
Check the details carefully. Make sure the name, address, and amount claimed are correct. Errors are more common than you might think, especially when debts have been sold or passed between collection agencies.
Confirm the type of debt. Different rules apply to different debts. Council tax, parking fines, and magistrates’ court fines are treated differently from credit cards or overdrafts. This affects what bailiffs can do and what options you have.
Do not ignore the notice. Ignoring it will not make it go away and may lead to higher fees and more pressure. Instead, use the time before any visit to get advice and explore solutions.
Seek independent debt quickly. Services like Stop Your Debt UK can review your situation, explain your bailiff rights, and help you negotiate affordable arrangements or consider longer-term solutions such as debt management plans or insolvency options if appropriate.
Protecting Yourself on the Day of a Bailiff Visit
If a bailiff does attend your property, you still have important protections. Remember, for most debts they cannot enter your home unless you invite them in or leave a door unlocked. You are allowed to speak through the door, a window, or not at all. You can ask them to put any information in writing or contact your adviser directly.
Keep doors and accessible windows locked and do not feel obliged to open the door just because they knock or call your name.
Ask for identification and details of the debt through the letterbox or a window. You are entitled to know who they are and why they are there.
Do not sign any documents or agree to unrealistic payments on the spot. Take time to check what you can genuinely afford.
If you already have support from a debt adviser, you can tell the bailiff that all communication should go through them. Many clients of Stop Your Debt UK find that once we are involved, the tone of debt collection changes dramatically and becomes more manageable and structured.
Regain Control Over Debt and Enforcement Action
Bailiffs and the Notice Of Enforcement process can feel like the storm at the centre of your debt problems. But knowledge is a powerful form of shelter. Understanding what bailiffs can and cannot do, recognising when they are using scare tactics, and knowing that they cannot break and enter or seize essential possessions like your work car or bike gives you the space to breathe and think clearly.
At Stop Your Debt UK, our role is to stand beside you in that storm. We combine expert knowledge of bailiff rights and debt collection law with a compassionate, non-judgemental approach. Whether you are facing council tax arrears, credit card debts, personal guarantees, or the threat of bankruptcy, we focus on giving you clarity, time, choice, and control so you can rebuild your financial health with confidence.
You do not have to deal with enforcement agents alone, and you do not have to make rushed decisions on the doorstep. Support is available, and with the right guidance, even serious debt situations can be turned around over time.
Take the next step: If you have received a Notice Of Enforcement or are worried about bailiffs, book a free consultation with Stop Your Debt UK. A confidential, personalised assessment can help you understand your options, protect your essential belongings, and start regaining control over your debts today.

Looking for an answer to a specific question?
Continue through the Knowledge Centre as we build a growing library of focused answers to common UK debt, court, creditor and director questions.
Start With the Question You're Trying to Answer.
Sometimes you don't need to understand the whole system. You need one clear answer.
These are the kinds of questions people commonly ask when dealing with creditors, court action, personal debt, personal guarantees and company financial difficulty.
What can debt collectors legally do in the UK?
Understand the difference between ordinary debt collection activity and formal enforcement powers.
What happens if I receive a CCJ?
Understand judgments, payment, registration, enforcement and the importance of the stage the case has reached.
Can a CCJ be set aside?
Explore what setting aside a judgment means and why the circumstances and procedural position matter.
Do I have to let a bailiff into my home?
Understand why enforcement powers, entry rules and the type of debt can affect what happens next.
Does resigning as a director cancel a personal guarantee?
Understand why leaving a company does not necessarily determine what happens to an existing guarantee.
What happens to a personal guarantee if the company becomes insolvent?
Explore the distinction between a company's liabilities and a director's potential personal exposure.
What happens when a company cannot pay its debts?
Understand the wider landscape of company financial difficulty and the formal processes that may become relevant.
What happens if a creditor petitions to wind up a company?
Understand the relationship between creditor action, winding-up proceedings and compulsory liquidation.
More questions. More detailed answers.
The Knowledge Centre is being expanded with focused resources covering the questions people search for when facing debt, creditor action, court proceedings and company financial difficulty.
Don't Just Read It. Understand What It Means.
A creditor or court letter can look more complicated than the underlying message.
LetterChekr™ helps turn correspondence into a structured, plain-English explanation, including the apparent priority or time sensitivity of the document and general information about what may be relevant next.
LetterChekr™ provides general information and document explanation. It is not legal advice or regulated debt advice. Where further professional support may be appropriate, this can be identified separately.
Get a clearer explanation of the correspondence in front of you.
Understand whether the document appears to contain deadlines or matters requiring closer attention.
Use the explanation as a clearer starting point for understanding the wider situation.
Understand the Situation. Then Decide What Comes Next.
The Knowledge Centre is here to help you make sense of the landscape. Your own circumstances determine what support may be appropriate.
If you have moved beyond general research and are dealing with creditor contact, court correspondence, personal debt, a personal guarantee or company financial difficulty, you can explore the wider support landscape or contact Stop Your Debt UK about your situation.
Choose the route that reflects where you are now.
Stop Your Debt UK provides permitted administrative support, document assistance and case coordination. Where regulated debt advice, legal advice, formal insolvency work or another specialist service is required, the appropriate work is carried out through suitably authorised or qualified professionals.
Better information creates clearer options. Understanding the position is the place to start.