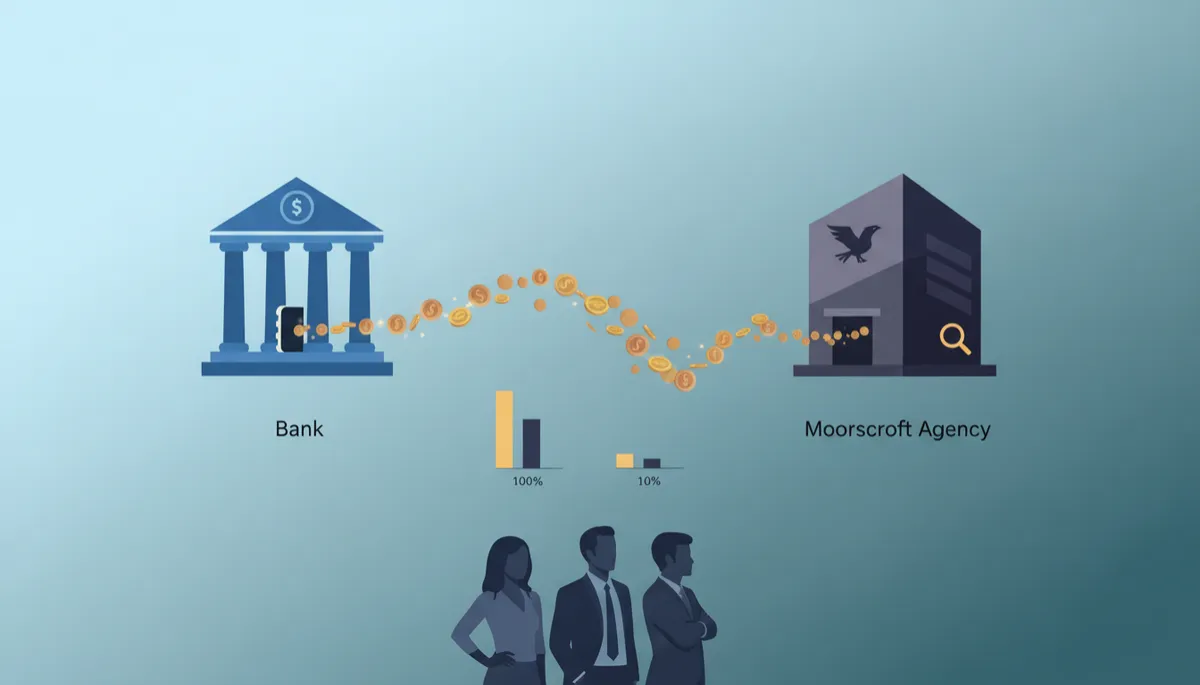
What Happens When a Bank Sells Your Debt to a Debt Collection Company?
Debt Collection, Bank Debt Sales, Moorcroft Agency, Debt Recovery Strategy
What Happens When a Bank Sells Your Debt to a Debt Collection Company?
If you are being chased by a Debt Collection agency like Moorcroft, it can feel as if your whole financial life is at risk. At Stop Your Debt UK, we help people understand what is really happening behind the scenes – including how banks sell debt for just a few pence in the pound, and how a structured Debt Recovery Strategy can mean you only repay a fraction of what you originally owe.
How Banks Sell Debt to Collection Agencies for Pennies
When you fall behind on credit cards, overdrafts or loans, banks will usually try to collect the money themselves for a period of time. They send reminder letters, make calls, and may add fees and interest. Eventually, many lenders decide that chasing the debt is no longer worth the cost and risk. At this point, they often package up thousands of overdue accounts and sell them to specialist companies in what is known as a Bank Debt Sales process.
These portfolios of unpaid debt are sold for a fraction of their face value. It is common for unsecured debts such as credit cards or personal loans to be sold for around 2–5 pence in the pound. In simple terms, a £10,000 balance that has gone bad for the bank might be sold on for only £200–£500. The buyer takes on the risk and the right to chase you for the full amount, hoping to collect more than they paid and make a profit in the process (see overviews from sources such as Investopedia and the Consumer Financial Protection Bureau).
For you as an individual, this hidden discount is important. It means the company contacting you may have bought your account very cheaply, and that creates room to negotiate. A realistic, well‑planned Debt Recovery Strategy can turn this to your advantage – especially when you are guided by a specialist service like Stop Your Debt UK.
Where Moorcroft Fits In – Collector, Agent or Buyer?
Moorcroft Debt Recovery Limited is one of the UK’s best‑known Debt Collection firms. According to its own website, Moorcroft usually works as an agent for banks, utilities and other creditors – collecting on their behalf rather than owning the debt itself. They are regulated by the Financial Conduct Authority (FCA) and are members of the Credit Services Association, with standards around fair treatment and vulnerable customers.
In practice, this means that when you receive a letter from the Moorcroft Agency, they may either be:
Collecting a balance that is still legally owned by your original bank or lender; or
Chasing a debt that has already been sold on, where another company now owns the account and has instructed Moorcroft to collect.
Either way, you have clear rights. You can ask for proof of the debt, confirmation of who owns it, and a full statement of account. Moorcroft’s own materials confirm that they must pause activity while disputes or certain complaints are investigated. At Stop Your Debt UK, we often start by helping clients request this information in a calm, structured way so they can see exactly what is being claimed before considering any repayment offers.
A clear plan turns frightening debt letters into manageable next steps.
Why Many People End Up Repaying Less – Without Repercussions
Because debts are often bought for 2–5p in the pound, there is usually significant room for negotiation. If a debt purchaser has paid £300 for a £10,000 account, accepting £1,000–£1,500 in a lump‑sum settlement can still represent a strong return for them. This is why, in many real‑world cases, a carefully negotiated full and final settlement can mean you repay less of what is outstanding, sometimes slightly more, sometimes less, depending on your circumstances and the creditor’s appetite to settle.
The key is to do this safely. Simply sending a small payment or informal offer can backfire if it restarts limitation periods or is not recorded correctly. At Stop Your Debt UK, we build a tailored Debt Recovery Strategy for each client that typically includes:
Verifying the debt is genuine, enforceable and not already statute‑barred.
Assessing your full financial picture – income, essential spending, priority debts and vulnerabilities.
Agreeing a realistic settlement range, often around 10–20% of the face value, based on what you can genuinely afford.
Negotiating in writing with the creditor or Debt Collection agency to reach a full and final settlement, with written confirmation that: the balance will be written off, no further action will be taken, and your credit file will be updated appropriately.
When this process is handled correctly, you can often draw a line under the debt after paying only a small proportion of the original balance. The “no repercussions” part comes from ensuring everything is documented: the creditor agrees in writing that they will not pursue the remaining balance or pass the account to another collector in future. This is how you protect yourself from fresh demands years later.
💡 Pro Tip: Never agree a lump‑sum payment or settlement over the phone. Always get any deal confirmed in writing, clearly marked as “full and final settlement”, before you send money.
Protecting Yourself While You Negotiate with Moorcroft or Other Agencies
Dealing with Moorcroft Agency or any other collector can feel intimidating, especially if you are also facing CCJs, business debts or personal guarantees. Yet UK regulation is clear: you are entitled to be treated fairly, to have your circumstances taken into account, and to dispute or question a debt without being harassed. Many people we support at Stop Your Debt UK find that once we step in, the tone of communication changes dramatically and the pressure eases.
Our role is not to help you “run away” from your responsibilities, but to ensure you only repay what is fair and affordable – and no more. When banks have already written off your account and sold it for a handful of pence in the pound, it is reasonable to question whether repaying the full amount is necessary or realistic. A structured approach can help you reach settlements that reflect this reality while rebuilding your financial health.
Take Back Control with Personalised Support
If you are receiving letters or calls about Bank Debt Sales, being chased by Moorcroft or another Debt Collection firm, or simply unsure how to start Repaying Debts safely, you do not have to face it alone. Stop Your Debt UK is built on compassion, clarity and empowerment. We take the time to understand your situation, explain your options in plain English, and design a Debt Recovery Strategy that gives you time, choice and control.
You may be much closer than you think to closing down old accounts for good – sometimes by paying less of what appears on the statement, with no further repercussions when it is done properly. The first step is to understand what your bank and the collectors have actually done with your debts, and then use that knowledge to negotiate from a position of strength.
Ready to regain control? Book a free consultation with Stop Your Debt UK today. We will review your letters, explain who really owns your debts, and help you explore realistic settlement options so you can move forward with confidence and peace of mind.
Received a debt collection letter?
If you've received correspondence from a creditor or debt collection company and you're unsure what it means, LetterChekr™ can provide a plain-English explanation of the document and highlight important information that may require your attention.
